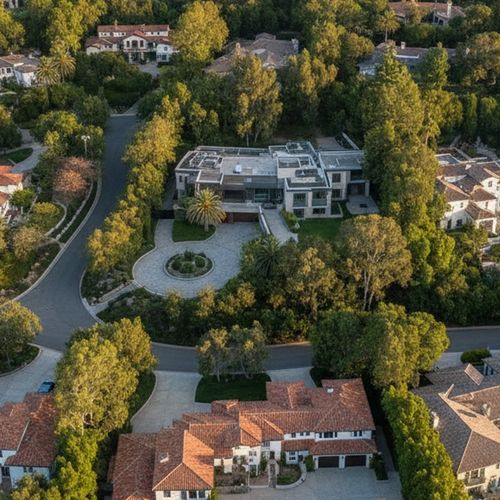
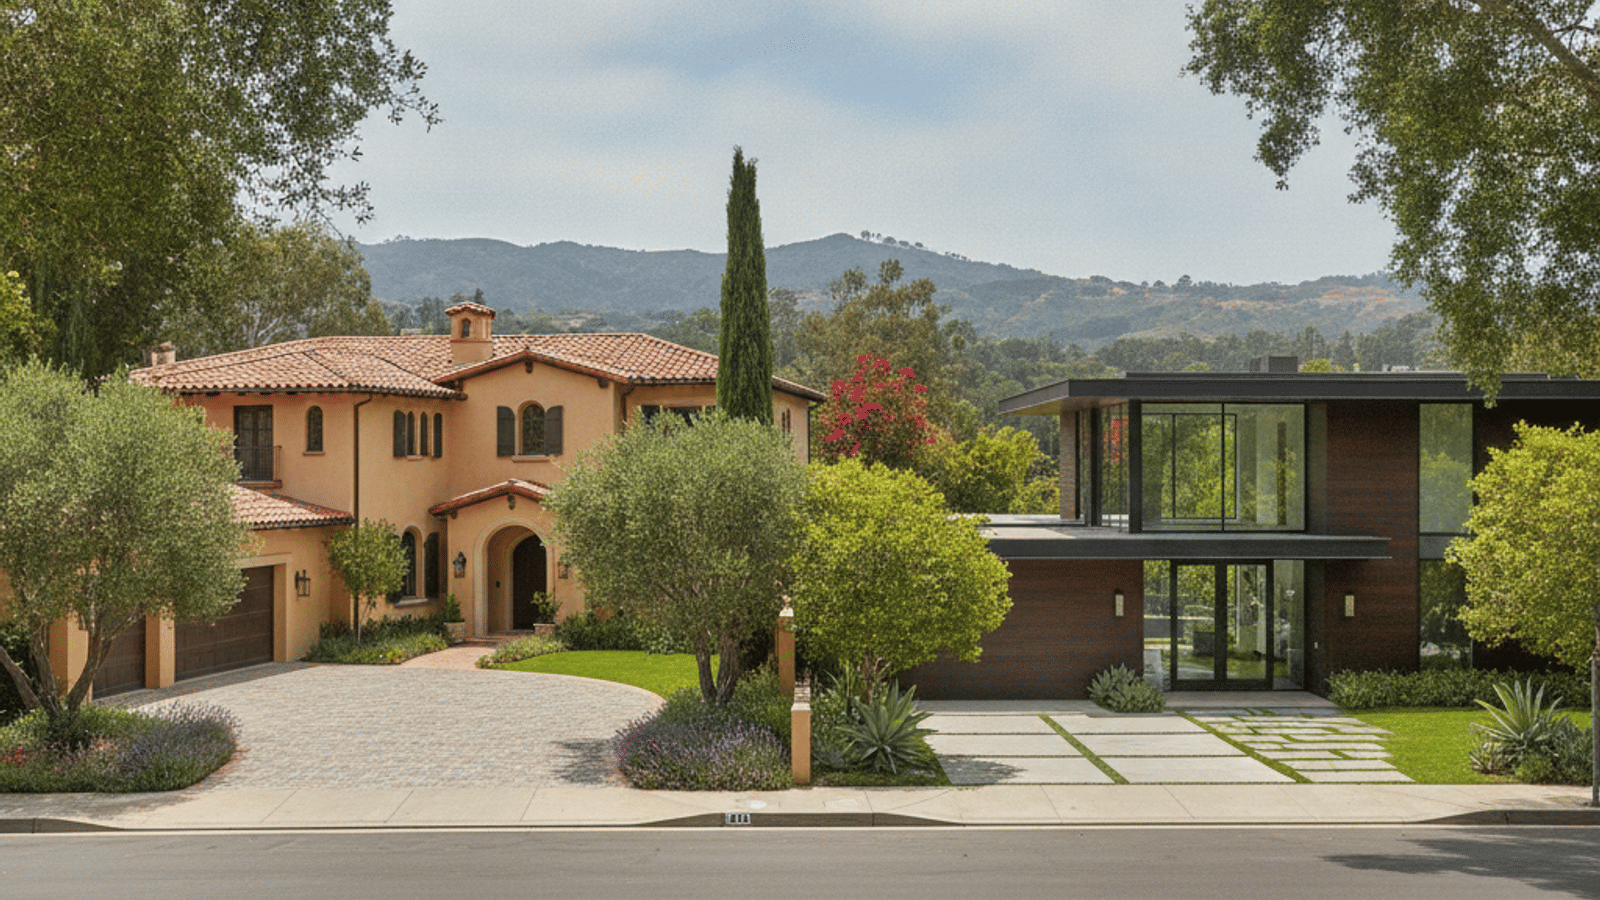
First-time home buyers in Montecito, CA face a median sale price far above most budgets, covered in the market section below, but they can enter through condos and townhomes and may qualify for Santa Barbara County and California down payment assistance if their income and purchase price fall within program caps.
Key Takeaway
Montecito's median sale price puts most single-family homes out of first-time reach, so condos and townhomes are the realistic entry. Local and state assistance exists, but income limits and lender price limits can exclude a Montecito purchase. Confirm program eligibility and whether you need a jumbo loan before you start touring.
Who This Guide Is For
This guide is for a first-time buyer pricing a Montecito purchase who wants to know which homes, loans and assistance programs are within reach.
Related guides: Buyer closing costs in Montecito, How much house can I afford in Montecito, Homebuyer programs in Montecito, Mortgage rates in Montecito, Types of homes in Montecito.
First-Time Buying in Montecito at a Glance
- Median sale price $5.4 million, 59 active listings (March 2026).
- Lowest recent condo sale: $1.5 million, plus monthly HOA dues.
- Workforce Homebuyer Program: up to $125,000, income at or below 210% of AMI.
- Dream For All: lesser of 20% or $150,000, repaid with appreciation share.
- One-unit conforming and FHA limit: $941,850; larger loans are jumbo.
The Montecito Real Estate Market Right Now
The latest figures from the Santa Barbara Association of Realtors (SBAOR) come from its March 2026 year-to-date snapshot. Montecito recorded 30 closed escrows, 16 pending sales and 59 active listings, with 3.7 months of inventory. The median sales price was $5.4 million, against $1.81 million for the South Coast as a whole and $2.23 million for the city of Santa Barbara.
That pool of listings is small. When a property matching your criteria comes up, you need financing lined up and the ability to act quickly. Ask your agent for the sale-to-list ratio on recent comparable sales. That ratio shows how much room you have to negotiate, and it helps you structure a competitive offer without overpaying.
Property Options for New Buyers
Condominiums are the most accessible homes in Montecito. In October 2025, the lowest-priced sale in Montecito was a condominium on Coast Village Road at $1,500,000, and that month's two condo sales had a median and average price of $3,375,000. These attached units cost far less than the multi-million dollar detached estates that make up the bulk of the local housing supply. Townhomes also come up occasionally. They offer a middle ground, with shared walls but slightly more square footage, often with private patios or small outdoor spaces.
Buyers targeting condominiums should factor Homeowner Association (HOA) dues into their monthly budget. These fees cover exterior maintenance and shared amenities. Dues vary widely from complex to complex, so request the current amount for any unit before you make an offer. Lenders count the full monthly HOA amount in your debt-to-income ratio during underwriting. A unit with higher dues can lower the maximum price you qualify for, even when its list price is lower.
Financial Assistance and Loan Programs
The South Coast Workforce Homebuyer Program, run by the Housing Trust Fund of Santa Barbara County (HTF), covers Montecito. It provides 10-year, simple-interest-only down payment loans of up to $125,000 to low- and middle-income workforce buyers in South County. You must work in Santa Barbara County, and household income cannot exceed 210% of Area Median Income for your household size. A Community Partner must certify your income. Ask HTF directly how a Montecito purchase price affects your application.
At the state level, the California Dream For All Shared Appreciation Loan from CalHFA covers up to 20% of the price or $150,000, whichever is less. At least one borrower must be a first-generation homebuyer, and every borrower must be a first-time buyer. For the 2026 cycle, household income in Santa Barbara County must be under $188,000. When you sell, refinance, pay off or transfer the first mortgage, you repay the original amount plus a share of appreciation. That share usually matches the percentage you borrowed. Borrowers who qualify for CalHFA's lower-income tier repay a lower share.
At the lowest recent condo price of $1.5 million, the program cap covers 10% of the price, so the remaining down payment and a large first mortgage still fall to you. Dream For All pairs with a CalHFA conventional first mortgage subject to CalHFA's sales price limits, so confirm with an approved lender whether a specific price qualifies.
Upfront and Ongoing Costs Beyond the Price
Loan type: For 2026, the one-unit loan limit in Santa Barbara County is $941,850 for both conforming (Fannie Mae and Freddie Mac) and FHA loans. A larger mortgage is a jumbo loan, which covers most Montecito purchases. Jumbo loans typically come with stricter down payment and cash-reserve expectations, so have your lender confirm the specifics before you set a budget.
Property tax: The county base rate is the Proposition 13 levy of 1%, and voter-approved bonds can be added on top. Most Montecito parcels carry a total rate very close to that 1% base, a bit higher where Santa Barbara Unified school bonds apply. The tax is assessed on your purchase price, so it grows with the price of the home and adds to the monthly payment a lender counts.
Insurance and fire zones: CAL FIRE updated its Fire Hazard Severity Zone maps in 2025, the first revision since 2009. The Montecito Fire Protection District states that the current mapping supports a Very High Fire Hazard Severity Zone designation for the community. When standard carriers decline to write a policy because of wildfire exposure, the California FAIR Plan acts as the state's insurer of last resort. It provides basic fire coverage, often paired with a separate difference-in-conditions (DIC) policy for other risks. Lenders require proof of insurance before they fund the loan, so get quotes during your contingency period.
Your lender and title company will itemize the remaining closing costs on your loan estimate and closing documents.
Schools, Parks, and Community Services
Properties in this area fall under the jurisdiction of the Montecito Union School District and the Cold Spring School District.
After sixth grade at either elementary school, students move into the Santa Barbara Unified School District for grades 7 through 12. Santa Barbara Junior High School is commonly cited as the middle school serving the area. Santa Barbara High School is the assigned public high school for most of Montecito, since there is no public high school within Montecito. Boundary lines set school assignments at every grade level, so check a specific address against district maps and confirm it with Santa Barbara Unified before relying on it.
Nearby amenities include Manning Park, Butterfly Beach along the southern coastal edge, and Santa Barbara Cottage Hospital in Santa Barbara, the primary medical center serving the region.
Commute Times and Infrastructure
US-101 is the main route connecting Montecito to downtown Santa Barbara and the wider region, so distance to its on-ramps sets your morning drive time. Foothill properties add winding, two-lane roads and steep grades before the highway, so a home with sweeping ocean views often means a longer drive. Drive the specific route during peak morning and evening hours before you commit to a home.
Public transit options are limited, so personal vehicles are the standard way to get around. Designated coastal paths support biking, but steep elevation changes inland make cycling impractical for daily errands.
How to Apply for Homebuyer Programs
Follow these steps in order before you write an offer:
- Talk to an approved lender: Choose a lender approved for the program you want, since only participating lenders can pair assistance with your first mortgage.
- Gather documents: Collect two years of tax returns, recent pay stubs and complete bank statements.
- Complete homebuyer education: Both programs require a HUD-approved homebuyer education class. Finish it and keep the certificate of completion for your file.
- Secure a voucher or reservation: For Dream For All, register during an open round and obtain a voucher. For the Workforce Homebuyer Program, complete income certification and reserve funds through your lender.
- Write the offer: Make an offer only once the assistance funds are committed to your purchase.
Dream For All runs in registration rounds, not continuous enrollment. Registration for the third round ran from February 24 to March 16, 2026, so watch CalHFA's announcements for the next one. The official application details and lists of participating lenders are on CalHFA's Dream For All page and the Housing Trust Fund of Santa Barbara County's Workforce Homebuyer Program page.
Frequently Asked Questions
Is California Giving Away $150,000 for First-Time Home Buyers?
No. That figure is the cap on Dream For All, which is a shared appreciation loan rather than a grant, so you repay it along with a share of the home's appreciation.
Are There Specific First-Time Home Buyer Programs Available in Montecito or Santa Barbara, CA?
Assistance is offered at the county, South Coast and state level, not for Montecito alone. The main options are the Housing Trust Fund's Workforce Homebuyer Program and CalHFA's Dream For All.
What Are the Income Requirements to Qualify for a Home Loan in Montecito?
Standard conventional loans do not have income caps, but assistance programs do, including the CalHFA county income limit for Dream For All. At Montecito prices, the real test is your lender's debt-to-income ratio.
How Do High Fire Risk Zones Impact Home Insurance Costs and Loan Approval for New Buyers in Montecito?
Fire zone status can narrow your insurer options and raise premiums, and your loan will not fund without proof of coverage.
Which Montecito Neighborhoods Offer the Best Commute Times and Access to Public Schools?
Homes south of East Valley Road and near the Lower Village sit closest to the US-101 on-ramps. For public schools, the address decides the assignment, not the neighborhood name.
Can I Use an FHA Loan to Buy a Montecito Condo?
Only if the loan stays within the one-unit FHA limit and the condo project appears on HUD's approved list, unless the unit qualifies as a site condominium or under FHA's single-unit approval. Search HUD's FHA-Approved Condominium tool by project name, city or ZIP code to see its status and expiration date. If the price requires a larger loan, you need a down payment that keeps the loan under the limit, or a jumbo loan.
Best Real Estate Agent in Montecito, CA: The Kogevinas Group
The Kogevinas Group, led by Principal Leader Nancy Kogevinas, brings a career sales volume of over $2.6 billion to the local market.
Sources
- Santa Barbara Association of Realtors March 2026 Montecito Figures
- Montecito Leads Santa Barbara South County Real Estate Market in October 2025, Montecito Journal
- Workforce Homebuyer Program, Housing Trust Fund of Santa Barbara County
- Dream For All Shared Appreciation Loan Program, CalHFA
- Opening the Door to Homeownership: The California Dream For All Program, SBAOR
- Dream For All, CalHFA
- FHA Loan Limits in California
- 2025-26 Tax Rate Book, Santa Barbara County
- Fire Hazard Severity Zones, Montecito Fire Protection District
- 24 CFR 203.43b, FHA Condominium Unit Eligibility
Check out this article next