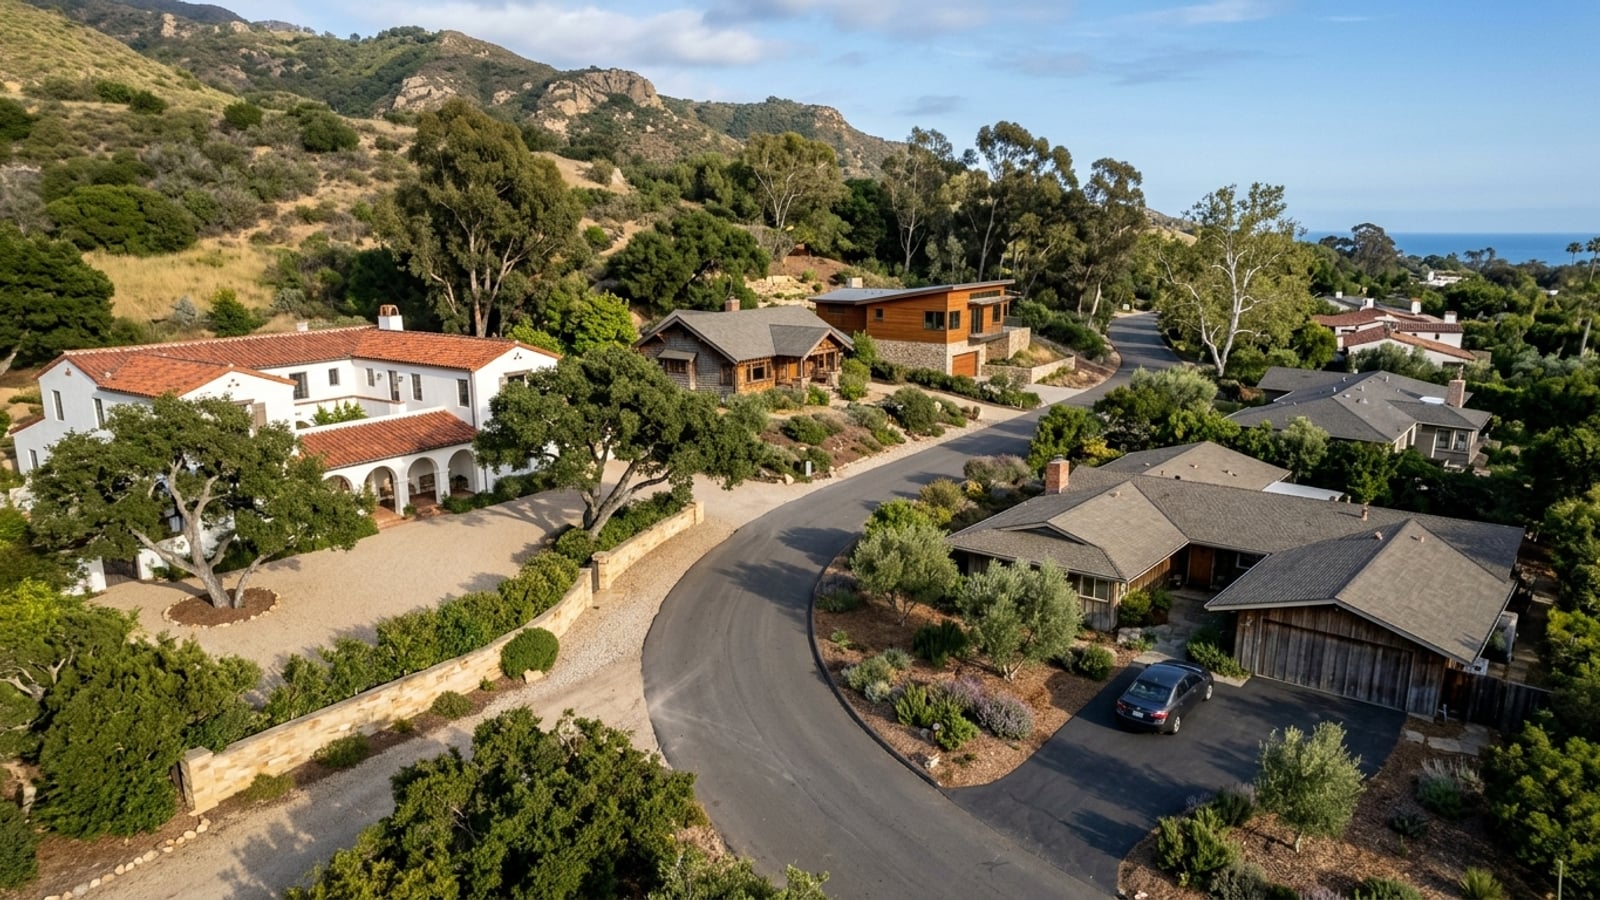
Montecito's real estate market operates on a different scale than most of California, which complicates the search for buyer assistance. Standard state and federal initiatives are designed around median prices that fall far below what you'll find on the South Coast.
Finding a program that helps with a purchase here means looking past the usual first-time buyer grants. You have to focus on loans with no maximum limit, tax-base transfers, or localized employer benefits that scale to the area's property values.
Key Takeaway
Most down payment assistance programs cap the purchase price far below Montecito's $6.2 million median sale price, so they rarely apply to market-rate homes here. The programs that do work at Montecito prices are VA loans with full entitlement and California's Prop 19 tax-base transfer. If you need assistance, Santa Barbara County's price-restricted homes or a purchase in a nearby community are the realistic alternative.
Who This Guide Is For
You're planning to buy in Montecito and want to know whether any assistance, loan, or tax program can lower your upfront or ongoing cost before you commit to a financing path.
Do Homebuyer Programs Work in Montecito?
Montecito's all-homes median of $6,197,049 (for the 90 days ending September 30, 2026) puts typical homes far beyond the purchase caps of standard down payment assistance programs. Putting that figure's standard down payment in cash leaves a loan near $4.96 million, more than five times the 2026 conforming loan limit of $941,850 for Santa Barbara County.
The programs that help a Montecito buyer are the ones without a low price cap: VA loans with full entitlement and Prop 19 tax-base transfers. Other realistic paths include Santa Barbara County's price-restricted homes and employer housing benefits, combined with a local market that leaves some room to negotiate seller credits.
Always confirm specific loan limits, program rules, and tax filing deadlines with the program administrator, a lender, and the county assessor.
Programs With Price Limits
Standard state and local down payment initiatives use county-wide income and purchase price maximums. Those caps dictate exactly where the funds can be applied.
Because Santa Barbara County's median prices are pulled down by other cities, the resulting program limits sit far below what a typical South Coast property costs. Buyers looking at Montecito must weigh whether they can find a qualifying property or whether they need to look outside the area entirely.
CalHFA loans and down payment assistance
The California Housing Finance Agency (CalHFA) offers first mortgages paired with assistance like the MyHome program and the Dream For All shared-appreciation loan. For 2026, CalHFA caps Santa Barbara County borrower income at $188,000 for standard programs and $235,000 for the Dream For All program. Dream For All provides up to 20% of the purchase price (capped at $150,000) for first-generation buyers, which is repaid with a share of the home's appreciation when you sell or refinance.
Funding rounds for programs like Dream For All open and close in short lottery windows, such as the brief period in early 2026. The deeper problem for Montecito buyers is that CalHFA's price caps rule out essentially every market-rate listing here. In practice, this program applies only to a price-restricted unit or a home outside Montecito. Ask CalHFA or a CalHFA-approved lender whether Dream For All or MyHome funding is currently open.
Housing Trust Fund of Santa Barbara County workforce homebuyer loans
The Housing Trust Fund of Santa Barbara County runs a South Coast Workforce Homebuyer Program that covers the Montecito area. It provides a 10-year, interest-only down payment loan up to $125,000 for low-to-middle-income buyers.
The program doesn't publish a strict maximum home purchase price, but eligibility is determined by household income limits. Ask the Trust whether a specific Montecito address qualifies before you build a budget around it.
FHA loans
FHA loans offer a low down payment option backed by the federal government, but the maximum FHA loan size is tied to the county's conforming limits, meaning the program can't finance a standard Montecito purchase. The county loan limit, combined with mandatory mortgage insurance, restricts FHA loans to properties priced at a tiny fraction of Montecito's typical sale. Very few Montecito condos come to market at all, and any complex you consider must have FHA project approval.
Programs That Work at Montecito Prices
When a home costs several million dollars, standard price-capped grants fall away. Buyers rely on programs that either place no limit on the purchase price or reduce the long-term cost of ownership.
These options don't lower the sticker price of the house. They focus on reducing your upfront cash requirement or shrinking your ongoing property tax burden year over year.
VA home loans
Veterans with full VA entitlement face no VA-imposed loan limit in 2026. The VA guarantees 25% of loans over $144,000 with no dollar cap, meaning a VA loan can reach jumbo amounts with no down payment required by the program itself. Borrowers pay a funding fee of 2.15% for first-time use with no down payment, or 3.30% for subsequent use, applied to the full loan amount unless exempt. California also offers the CalVet program, which carries its own separate loan limits.
With full entitlement, the VA sets no loan limit, so the cap that matters is the lender's. Individual lenders set their own maximums and reserve requirements for large VA loans, and those numbers vary more than you'd expect. Ask at least two lenders for their maximum VA loan amount and reserve requirements on a jumbo VA purchase.
Prop 19 base-year value transfer
Under California Proposition 19, homeowners who are 55 or older, severely disabled, or victims of a natural disaster can carry their current property tax assessed value to a replacement home anywhere in the state. This can be done up to three times, and claimants must file within three years of purchasing the replacement dwelling. Prop 19 lets an eligible owner move their old tax base to a home anywhere in California, not just within the same county as under the old rules.
You can review your property tax bill to see how this affects your monthly costs. One important wrinkle: if the Montecito replacement home costs more than your original home's market value, the difference is added to your transferred base year value. That adjustment can shrink your tax savings considerably. Ask the Santa Barbara County Assessor for the claim form and confirm your filing deadline before closing.
Price-Restricted Homes and Workforce Housing
Buyers who need assistance on the South Coast often turn to programs that trade market freedom for a lower entry price. These options depend on county inventory or your specific employer rather than a standard bank loan.
Taking this route means accepting specific rules about who can buy the home and how much it can appreciate. Qualifying units rarely come to market, so flexibility on location and timing isn't optional.
Santa Barbara County affordable ownership homes
Santa Barbara County promotes affordable housing through its Inclusionary Housing Program, which creates resale-restricted units in unincorporated areas like Montecito. These homes are sold at controlled prices to income-qualified buyers. For 2026, the state sets the county's low-income limit equal to its moderate-income limit (120% of the area median income).
No specific Montecito inventory is currently listed on the county's official pages, so you'll need to look across the broader South Coast. What you give up is equity growth: resale price controls cap how much the home can gain in value, and strict occupancy rules apply. Ask Santa Barbara County Housing and Community Development about current price-restricted ownership listings and waitlist length.
Employer-assisted housing
The Coastal Housing Partnership is a non-profit that works with local employers to offer homebuying benefits in Santa Barbara County. Employees of member companies get access to a network of real estate agents, lenders, and inspectors who provide credits toward closing costs, including a commission credit capped at $7,500. There are no income restrictions or first-time buyer requirements to use these benefits.
The benefit depends entirely on your employer, not the home itself. Ask your HR department whether your company belongs to the partnership or offers its own housing benefit.
How to Choose a Homebuyer Program in Montecito
Your financing path depends on your purchase price, your military background, and your employer.
- Will your purchase price fall under the program's sales price or loan cap? If not, skip the capped programs and look at options that work at Montecito prices.
- Do you have VA loan entitlement, or are you selling a California home in a situation Prop 19 covers? If so, start with the VA home loans or Prop 19 base-year value transfer sections.
- Would you accept income limits and a capped resale price in exchange for a much lower purchase price? If so, check the county's affordable housing waitlist.
- Does your employer offer a housing benefit or belong to Coastal Housing Partnership? If so, read the employer-assisted housing section before you shop for a lender.
If you want to use CalHFA, FHA, or a county down payment loan, start with Santa Barbara County's price-restricted ownership homes, or compare options in Carpinteria and Summerland, because program sales price caps sit far below Montecito's median. If you want a low down payment loan on a market-rate Montecito home, start with a VA home loan, because the VA sets no loan limit with full entitlement. If you want to lower the ongoing cost of a Montecito home after selling a California home, start with a Prop 19 base-year value transfer, because it carries your existing assessed value to the new home.
If standard programs rule out a Montecito purchase, reviewing a first-time buyer market guide can help you map out alternatives across Santa Barbara.
Montecito Housing Market for Financed Buyers
Buyers who can't use a specific assistance program can still find help with closing costs by negotiating directly with the seller.
Recent market data shows an all-homes sale-to-list ratio of 98.2% and 5.2 months of supply. Sellers typically accept a little under asking price, and buyers have time to negotiate. You can use that room to ask for seller credits toward your closing costs or a temporary mortgage rate buydown, which often saves more cash upfront than a capped county program. That said, some properties are competitive, and a portion of homes still sell above list price. Ask your lender the maximum seller credit your loan type allows at your specific down payment tier. For a broader look at where prices are heading, review the housing market trends and forecast.
At a Glance
- Median sale price, all homes: $6,197,049, up 2% year over year (90 days ending 2026-09-30, 40 sales)
- Median sale price, single family: $6,997,210, up 12% year over year (90 days ending 2026-09-30, 31 sales)
- Median days on market: 59 for all homes, 72 for single family (90 days ending 2026-09-30)
- Sale-to-list ratio: 98.8% for single family (90 days ending 2026-09-30)
- Share sold above list: 15.4% of all homes, 19.4% of single family (90 days ending 2026-09-30)
- Months of supply: 6.1 for single family (90 days ending 2026-09-30)
- Active inventory: 67 all homes, of which 63 single family (90 days ending 2026-09-30)
- Median price per square foot: $1,842 for all homes, $1,805 for single family (90 days ending 2026-09-30)
Montecito Homebuyer Programs FAQs
What county is Montecito, CA in, and which county programs apply?
Montecito is an unincorporated community in Santa Barbara County, so county programs govern it. The California Department of Housing and Community Development (HCD) sets income limits for the county, classifying it as one of three counties in the state where the low-income limit equals the moderate-income limit for 2026.
Who qualifies as a first-time home buyer in California?
CalHFA defines a first-time homebuyer as someone who has not had an ownership interest in a principal residence in the previous three years. This also includes not residing in a home owned by a spouse during that time. This definition matters primarily for price-capped programs rather than market-rate Montecito purchases.
Are there first-time home buyer grants in California?
Most state assistance comes as deferred or shared-appreciation loans rather than true grants. CalHFA's Dream For All program, for example, provides assistance capped at $150,000 for down payment and closing costs, repaid with a share of the home's appreciation when sold or refinanced. No true outright grant program is listed for Santa Barbara County.
What are the income limits for homebuyer programs in Santa Barbara County?
For 2026, the CalHFA income limit for Santa Barbara County is $188,000 for standard programs and $235,000 for the Dream For All Shared Appreciation Loan. The county's affordable-ownership income categories are set by the state, with the low-income limit matching the 120%-of-AMI moderate-income calculation.
What is the minimum down payment for a jumbo loan in Montecito?
Any loan above the Santa Barbara County conforming limit is a jumbo loan; the 2026 limit is $941,850. Jumbo down payment minimums are set by individual lenders rather than a government program. Ask several lenders for their specific minimum down payment and reserve requirements at your target loan size.
Do I need a homebuyer education course to use a California assistance program?
Yes, CalHFA requires at least one occupying first-time homebuyer to complete an education course. This can be done online through eHome for a $100 fee, or in-person through a HUD-Approved Housing Counseling Agency. You should complete this course before closing.
Sources
- Redfin: Data Center
- CalHFA Dream For All Program
- CalHFA Program Bulletin 2026-07
- CalHFA First-Time Homebuyer Definition
- CalHFA Homebuyer Education
- Alpine Bank Conforming Loan Limits
- Housing Trust Fund of Santa Barbara County
- US Code VA Loan Limits and Fees
- California BOE Prop 19
- Santa Barbara County Affordable Housing Resource Guide
- California HCD 2026 Income Limits
- Coastal Housing Partnership
- HUD FHA Condominium Lookup
Check out this article next